
The Difference Between a 401(k), IRA, and Roth IRA
D
By Drew Larson on November 12, 2026
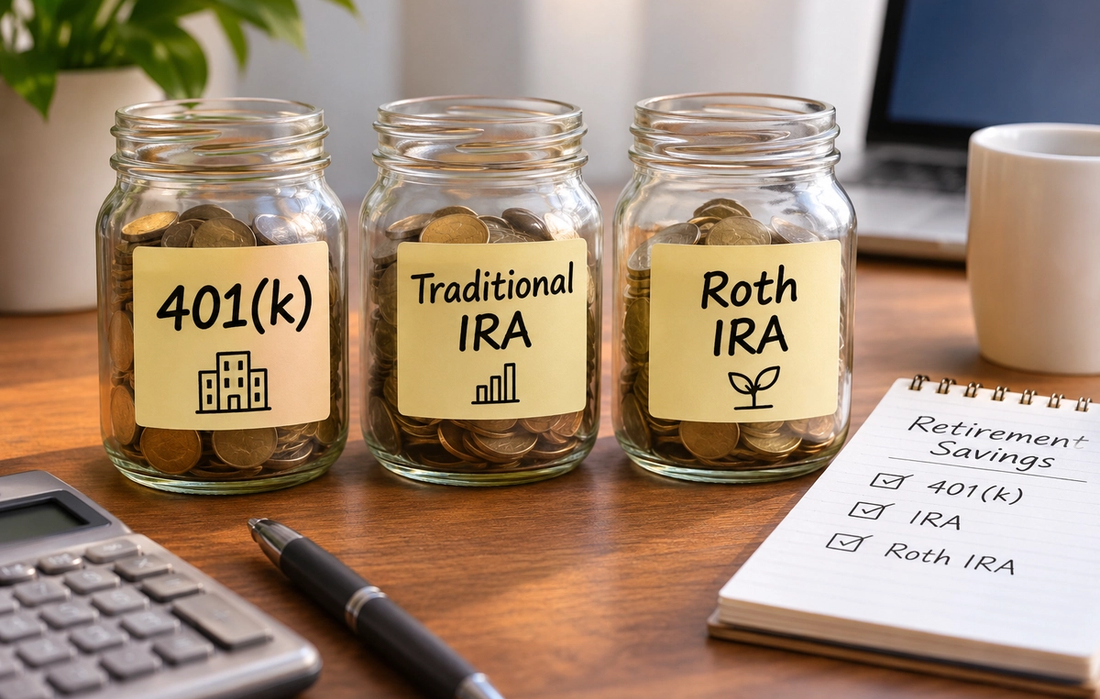
Retirement accounts come with enough acronyms and tax terminology to make saving for the future sound much harder than it needs to be. Three names appear particularly often in the United States: the 401(k), traditional IRA, and Roth IRA. All three can help you save and invest for retirement, but they differ in who provides them, how contributions are taxed, and how withdrawals are treated.
A 401(k) Comes Through an Employer
A 401(k) is a workplace retirement plan offered by many employers. Contributions are generally deducted directly from your paycheck, and you can invest the money using the options available within your plan.
Traditional 401(k) contributions are generally made before federal income tax, reducing taxable income today, while withdrawals are generally taxable in retirement. Some employers also match part of an employee’s contribution. When a match is available, it can be an especially valuable part of the plan because your employer is contributing additional money toward your retirement.
A Traditional IRA Is an Individual Account
IRA stands for Individual Retirement Arrangement, although it’s commonly called an Individual Retirement Account. Unlike a 401(k), you generally open an IRA yourself through a financial institution.
With a traditional IRA, eligible contributions may be tax-deductible depending on factors such as income and participation in a workplace retirement plan. Investments can then grow tax-deferred, with withdrawals generally taxed as income in retirement.
A Roth IRA Reverses the Tax Timing
A Roth IRA is also an individual retirement account, but the tax treatment works differently. Contributions are made with money that has already been taxed, so you don’t receive a deduction simply for making a Roth contribution. In exchange, qualified withdrawals in retirement are generally tax-free.
That can make Roth accounts attractive to people who would rather pay taxes on the money now than potentially pay them on qualified withdrawals later. However, Roth IRA contributions are subject to income eligibility rules.
You Don’t Necessarily Have to Choose Just One
A 401(k), traditional IRA, and Roth IRA aren’t mutually exclusive. Depending on your eligibility and financial circumstances, you may be able to contribute to more than one type of retirement account. Each also has its own annual contribution limits and rules, which can change over time.
The easiest distinction to remember is this: a 401(k) is primarily an employer-sponsored retirement plan, a traditional IRA is an individually opened account that may provide a tax deduction now, and a Roth IRA uses after-tax contributions in exchange for tax-free qualified withdrawals later.
The details matter, particularly because tax rules and contribution limits change. But once you understand when the tax benefit happens—today or in retirement—the differences between these accounts become much easier to follow.
Why Older Millennials Are the Last Generation to Remember Pre-Internet Life
Older millennials occupy a strange place in technological history. They grew up with television, landlines, paper maps, handwritten notes, and afternoons when nobody knew exactly where their friends were.
Asaf Been|5m ago
The Quiet Loneliness of the Always-Busy Generation
Roi Kad|11m ago
Why “Having It All” Was Always a Trade-Off for Us Too
German Smolyar|14m ago
The Real Difference Between Being Busy and Being Effective
Julian Doyle|17m ago
Why Older Millennials Feel Like the Forgotten Generation
Moran Sally|20m ago
The Hidden Cost of Being the First Generation to Figure It Out Online
Drew Larson|22m ago
Read More
Why Older Millennials Are the Last Generation to Remember Pre-Internet Life
Asaf Been|
The Quiet Loneliness of the Always-Busy Generation
Roi Kad|
Why “Having It All” Was Always a Trade-Off for Us Too
German Smolyar|
The Real Difference Between Being Busy and Being Effective
Julian Doyle|
Why Older Millennials Feel Like the Forgotten Generation
Moran Sally|
The Hidden Cost of Being the First Generation to Figure It Out Online
Drew Larson|