
The 50/30/20 Budget Explained
R
By Roi Kad on November 12, 2026
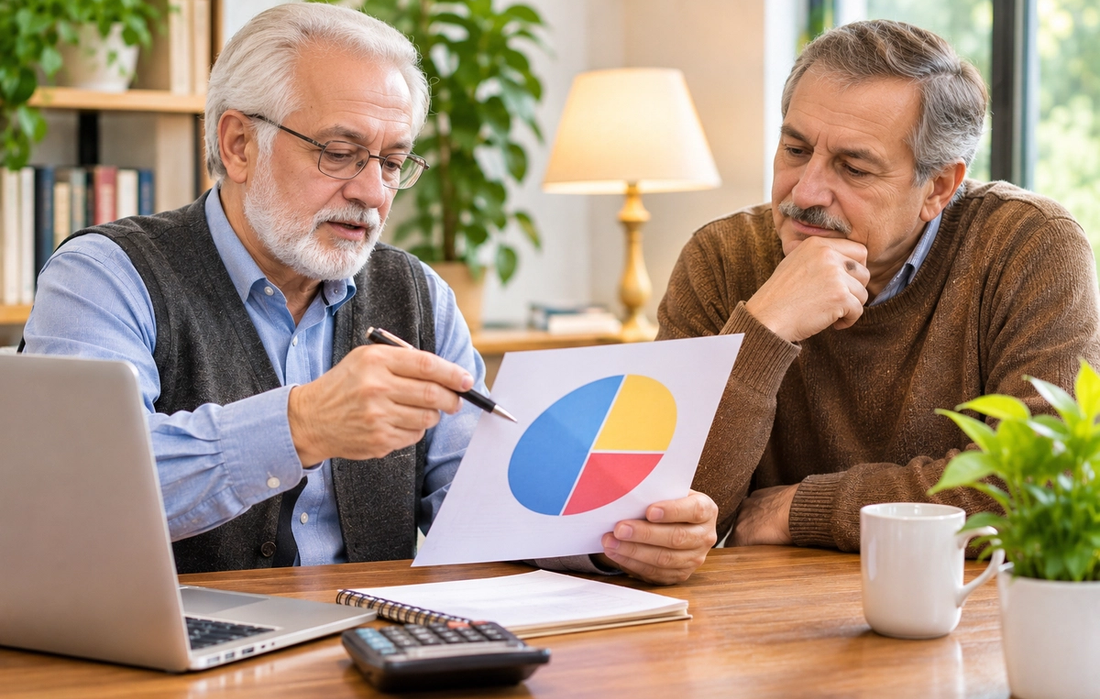
Budgeting can become complicated surprisingly quickly. There are spreadsheets, expense categories, financial apps, and rules for nearly every type of purchase. The 50/30/20 budget offers a simpler approach: divide your take-home income into three broad categories—needs, wants, and financial goals.
50% Goes to Needs
The first half of your after-tax income is intended for essential expenses. That usually includes housing, utilities, groceries, transportation, insurance, minimum debt payments, and other bills you genuinely need to pay. The important distinction is necessity. A basic internet plan you need for work may belong here, while several entertainment subscriptions probably don’t.
If your essential expenses already exceed 50%, that doesn’t mean you’ve failed at budgeting. Housing costs, family circumstances, location, and income can make this target unrealistic. Think of the percentage as a guideline rather than a rule you must obey.
30% Goes to Wants
The next 30% is for things that make life more enjoyable but aren’t strictly necessary. Restaurants, vacations, entertainment, hobbies, shopping, streaming services, and other discretionary spending generally fit here. This category is important because a sustainable budget shouldn’t require eliminating everything enjoyable.
It is also the category with the most flexibility. If you need to free up money temporarily, reducing wants is often easier than dramatically changing rent, transportation, or other fixed expenses.
20% Goes to Savings and Financial Goals
The remaining 20% is directed toward improving your financial future. Depending on your situation, that might mean building an emergency fund, investing for retirement, saving toward a major goal, or making debt payments beyond the required minimum.
Automating this portion can make the system easier. Moving money into savings or investments shortly after you’re paid means you don’t have to rely on whatever happens to remain at the end of the month.
The Percentages Can Change
The biggest mistake is treating 50/30/20 as a universal formula. Someone living in an expensive city might need 60% for necessities. Someone aggressively saving for a home might choose to spend only 20% on wants and save 30%. Your percentages can evolve as your income, responsibilities, and priorities change.
The real value of the 50/30/20 budget isn’t mathematical perfection. It gives every paycheck three jobs: pay for life today, leave room to enjoy it, and put something aside for tomorrow. If those exact percentages don’t fit your circumstances, adjust them. A budget that works imperfectly in real life is far more useful than a perfect one you can’t maintain.
Why Older Millennials Are the Last Generation to Remember Pre-Internet Life
Older millennials occupy a strange place in technological history. They grew up with television, landlines, paper maps, handwritten notes, and afternoons when nobody knew exactly where their friends were.
Asaf Been|5m ago
The Quiet Loneliness of the Always-Busy Generation
Roi Kad|11m ago
Why “Having It All” Was Always a Trade-Off for Us Too
German Smolyar|14m ago
The Real Difference Between Being Busy and Being Effective
Julian Doyle|17m ago
Why Older Millennials Feel Like the Forgotten Generation
Moran Sally|20m ago
The Hidden Cost of Being the First Generation to Figure It Out Online
Drew Larson|22m ago
Read More
Why Older Millennials Are the Last Generation to Remember Pre-Internet Life
Asaf Been|
The Quiet Loneliness of the Always-Busy Generation
Roi Kad|
Why “Having It All” Was Always a Trade-Off for Us Too
German Smolyar|
The Real Difference Between Being Busy and Being Effective
Julian Doyle|
Why Older Millennials Feel Like the Forgotten Generation
Moran Sally|
The Hidden Cost of Being the First Generation to Figure It Out Online
Drew Larson|