
How to Pay Off Debt Faster: Snowball vs. Avalanche
M
By Moran Sally on November 12, 2026
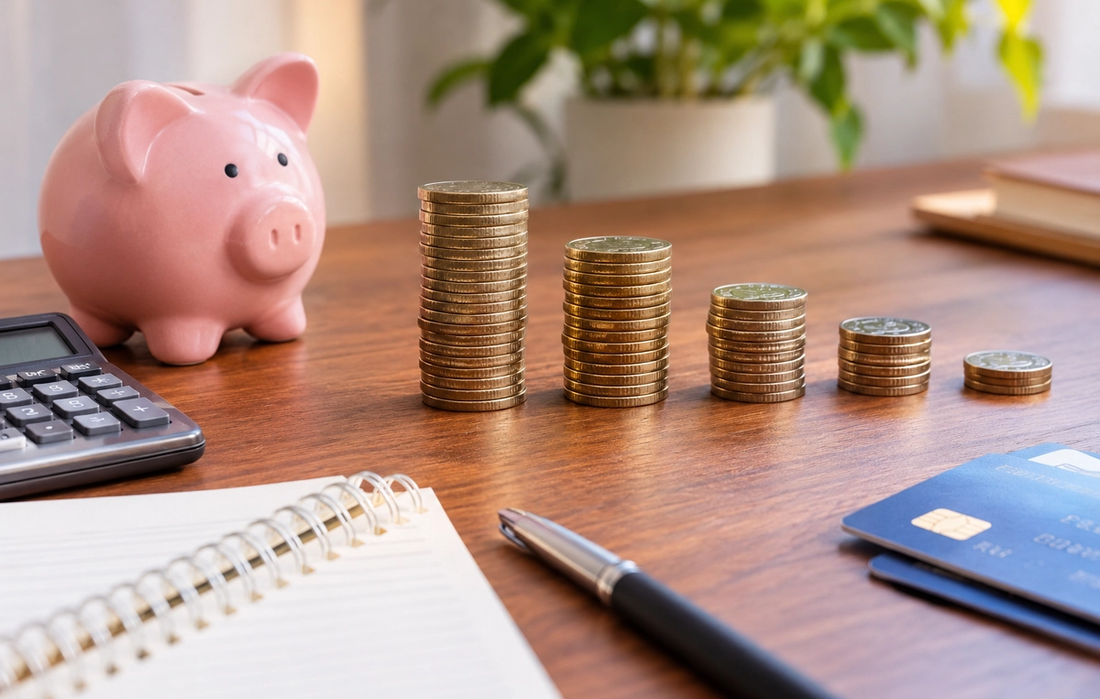
Paying off several debts at once can feel frustrating because progress is spread across multiple balances. Two popular strategies simplify the process: the debt snowball and the debt avalanche. Both involve making the minimum payment on every debt while directing extra money toward one balance at a time. The difference is which debt you attack first.
The Debt Snowball Starts With the Smallest Balance
With the snowball method, you list your debts from smallest balance to largest, regardless of their interest rates. Put as much extra money as possible toward the smallest debt while continuing minimum payments on everything else. Once that balance is gone, move the money you were paying toward it onto the next-smallest debt.
The advantage is psychological. Paying off an entire balance relatively quickly creates a visible win and reduces the number of bills you’re managing. For someone who has struggled to stay motivated, that momentum can be extremely valuable.
The Debt Avalanche Targets the Highest Interest Rate
The avalanche method takes a different approach. Instead of looking at balances, you prioritize the debt charging the highest interest rate. Once it’s paid off, you move to the debt with the next-highest rate.
Mathematically, this is generally the cheaper strategy because you’re attacking the debt that is costing you the most first. If you stay consistent, the avalanche can reduce the total interest you pay and may help you become debt-free sooner.
Which Method Is Better?
On paper, the avalanche usually wins because it minimizes interest. In real life, however, the best method is the one you can actually maintain. If eliminating a small balance quickly gives you enough motivation to keep going, the snowball may work better for you even if it costs somewhat more in interest.
You can also combine the approaches. Paying off one very small balance first can create an early victory, after which you can switch to prioritizing high-interest debt.
The Strategy Matters Less Than Consistency
Whichever method you choose, avoid adding new debt where possible and continue making at least the required minimum payments on every account. Whenever one balance disappears, redirect that entire payment toward the next target instead of allowing the money to disappear back into everyday spending.
Debt repayment isn’t usually transformed by one dramatic payment. It’s the repeated decision to keep directing available money toward the next balance. Snowball gives you faster psychological wins; avalanche gives you greater mathematical efficiency. Choose the one that makes you most likely to keep going until the final balance reaches zero.
Why Older Millennials Are the Last Generation to Remember Pre-Internet Life
Older millennials occupy a strange place in technological history. They grew up with television, landlines, paper maps, handwritten notes, and afternoons when nobody knew exactly where their friends were.
Asaf Been|5m ago
The Quiet Loneliness of the Always-Busy Generation
Roi Kad|11m ago
Why “Having It All” Was Always a Trade-Off for Us Too
German Smolyar|14m ago
The Real Difference Between Being Busy and Being Effective
Julian Doyle|17m ago
Why Older Millennials Feel Like the Forgotten Generation
Moran Sally|20m ago
The Hidden Cost of Being the First Generation to Figure It Out Online
Drew Larson|22m ago
Read More
Why Older Millennials Are the Last Generation to Remember Pre-Internet Life
Asaf Been|
The Quiet Loneliness of the Always-Busy Generation
Roi Kad|
Why “Having It All” Was Always a Trade-Off for Us Too
German Smolyar|
The Real Difference Between Being Busy and Being Effective
Julian Doyle|
Why Older Millennials Feel Like the Forgotten Generation
Moran Sally|
The Hidden Cost of Being the First Generation to Figure It Out Online
Drew Larson|